S Corp vs C Corp vs LLC – Which Business Structure is Right for You? - CPA Pilot
federal tax automation
S Corp vs C Corp vs LLC: Taxes, Costs & Differences
Compare S Corp vs C Corp vs LLC structures, including key differences in taxation, liability, ownership, and costs. Explore real tax examples, potential savings, and practical insights to help you choose the right business structure in 2026.
CPA Pilot
Oct 11, 2026·18 min read
What You'll Learn
4 key concepts covered
1How LLC, S Corp, and C Corp taxation differs at federal level.
2When S Corp election can reduce employment taxes for owners.
3Ownership, investor, and stock limitations that affect fundraising options.
4Administrative costs, payroll requirements, and profit distribution rules for each.
Choosing between an S Corporation (S Corp), C Corporation (C Corp), and Limited Liability Company (LLC) affects how your business pays taxes, protects its owners, distributes profits, and raises capital. The right choice depends on your income, ownership structure, operating costs, and long-term business goals.
An LLC offers flexible management and federal tax classification. An S Corp election can provide pass-through taxation and potential employment tax savings for eligible businesses. A C Corp offers greater flexibility for outside investment but may expose distributed profits to two levels of taxation.
Understanding these differences is essential before forming a business or changing its tax treatment.
Quick Answer: S Corp vs C Corp vs LLC — Which Is Better?
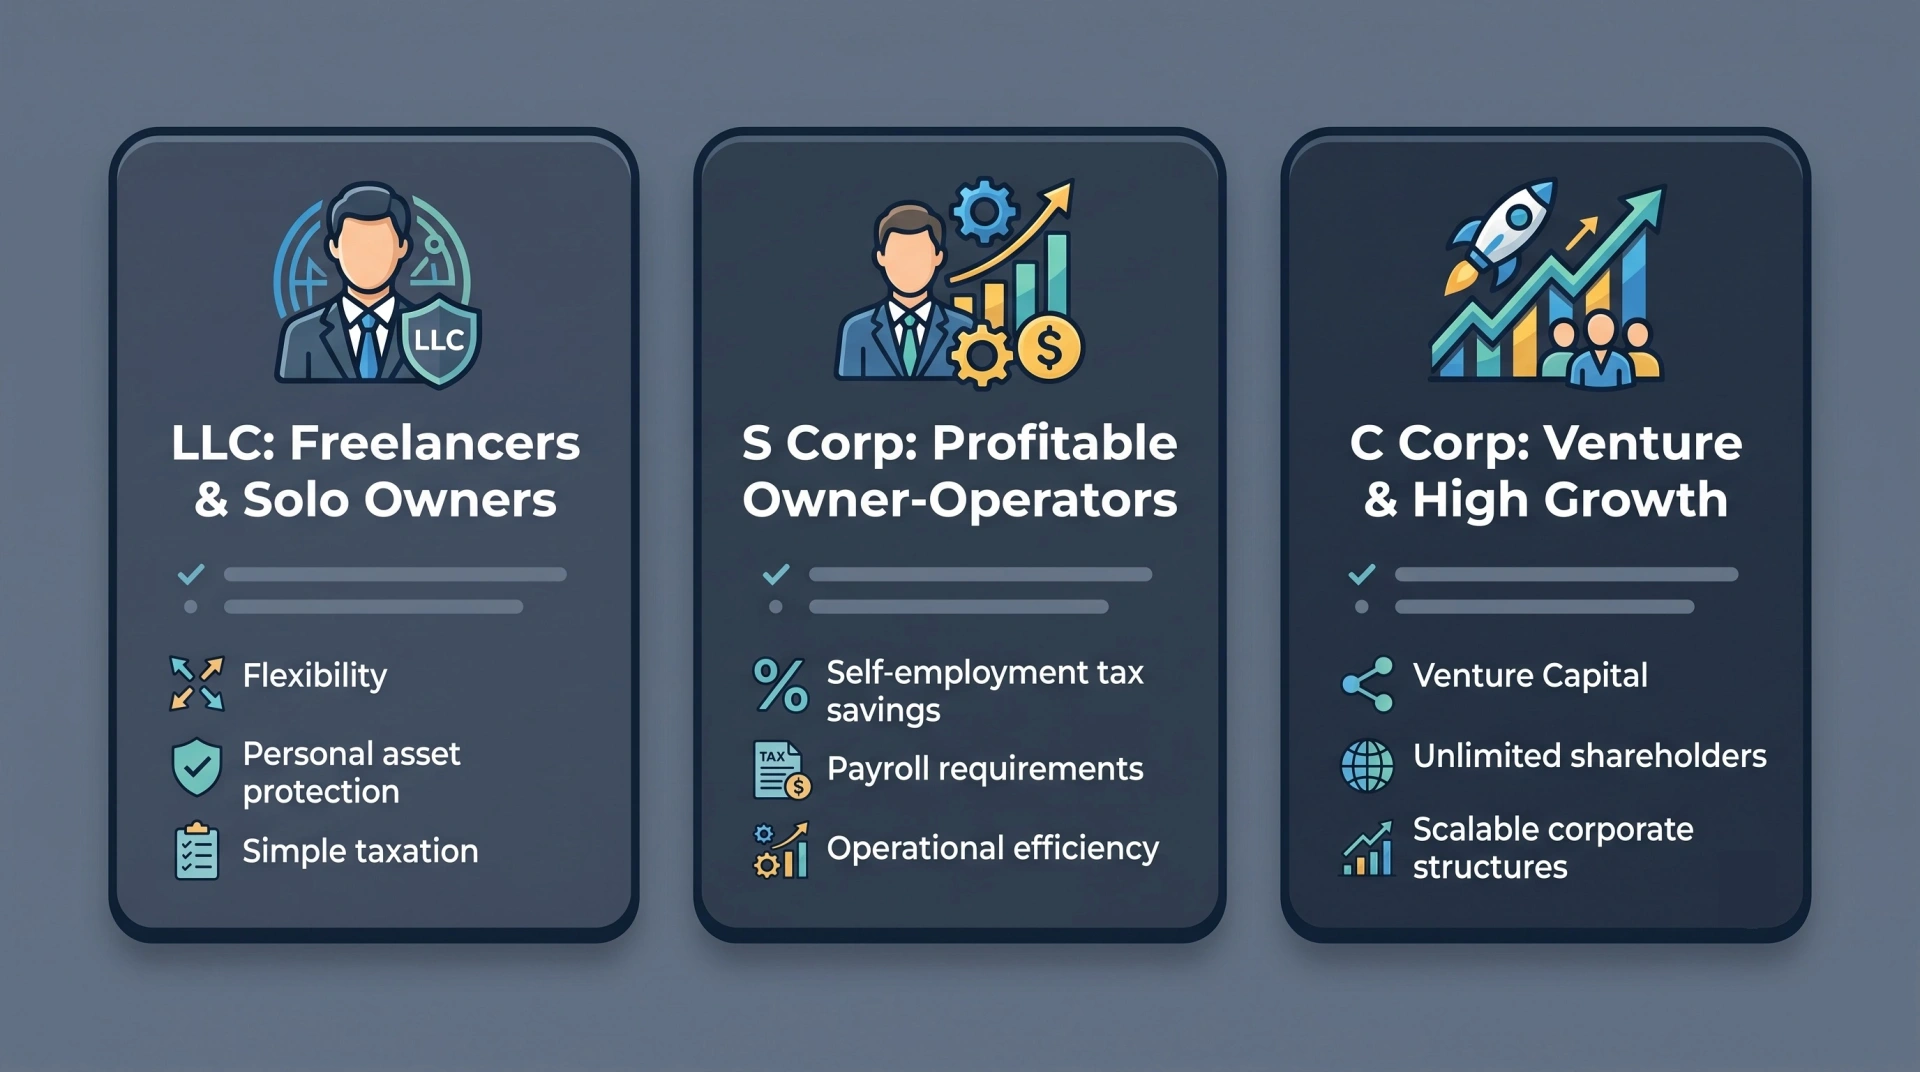
LLC: Often best for freelancers, small businesses, and owners who want flexible management, liability protection, and straightforward default taxation.
S Corp: Often best for eligible profitable businesses where reasonable owner compensation leaves sufficient earnings to justify additional payroll and compliance costs.
C Corp: Often best for venture-backed startups, businesses seeking multiple stock classes, or companies planning substantial equity investment.
The key distinction: An LLC is a legal entity formed under state law, while S Corp is a federal tax classification. An eligible LLC can elect to be taxed as an S Corp without becoming a corporation under state law.
There is no universally best structure. The most tax-efficient option depends on total federal and state taxes, owner compensation, available deductions, and the cost of maintaining the entity.
S Corp vs C Corp vs LLC: Key Differences at a Glance
The main differences between an LLC, S Corp, and C Corp involve taxation, ownership restrictions, profit distributions, and administrative requirements.
Feature
LLC (Default Taxation)
S Corp Taxation
C Corp Taxation
Legal structure
State-law LLC
Eligible LLC or corporation
Corporation or LLC electing corporate taxation
Federal income taxation
Pass-through by default
Pass-through, with certain exceptions
Corporation pays federal income tax
Federal tax rate
Individual owner rates
Individual shareholder rates
21% corporate rate
Employment taxes
Self-employment tax may apply to qualifying owner earnings
Wages subject to payroll taxes; qualifying distributions generally are not
Wages subject to payroll taxes; dividends generally are not
Ownership
Flexible; state rules apply
Generally up to 100 eligible shareholders
No general shareholder-number limit
Foreign ownership
Generally permitted
Nonresident alien shareholders generally prohibited
Permitted
Equity flexibility
Membership interests
One class of stock for economic rights
Multiple stock classes
Profit distributions
Generally flexible under governing agreement and tax rules
Must respect identical economic distribution rights
Based on stock rights
Management
Member-managed or manager-managed
Depends on underlying legal entity
Corporate board and officers
Administrative burden
Often lower under default taxation
Payroll and separate federal tax return
Separate federal tax return and corporate formalities
Common fit
Freelancers, small teams, flexible ownership
Profitable owner-operated businesses
Venture-backed and equity-focused companies
These distinctions matter because legal structure and tax classification are separate decisions.
LLC vs S Corp vs C Corp: What Do These Terms Mean?
Limited Liability Company (LLC): A business entity created under state law. Owners are called members. A single-member LLC is generally disregarded for federal income tax purposes by default, while a domestic multi-member LLC is generally taxed as a partnership unless it elects otherwise.
S Corporation: A federal tax status available to eligible domestic corporations and certain other entities, including LLCs. Income, deductions, losses, and credits generally pass through to shareholders rather than being subject to regular federal corporate income tax.
C Corporation: The default federal tax classification for a corporation. The corporation generally pays income tax on its taxable profits, and shareholders may pay additional tax when those earnings are distributed as dividends.
For example, an entrepreneur can establish an LLC under state law and later elect S Corp taxation through the IRS. The LLC remains an LLC legally, but its federal income tax treatment changes.
Taxation is often the most financially significant difference between business structures. However, comparing tax rates alone can be misleading. Owner wages, business deductions, profit distributions, and state taxation can substantially change the result.
1. LLC Taxation: Single-Member vs Multi-Member LLC
An LLC's default federal tax treatment depends on the number of owners.
A single-member LLC is generally treated as a disregarded entity for federal income tax purposes. If an individual owns and actively operates the business, income and expenses are usually reported on Schedule C of Form 1040.
A multi-member LLC is generally taxed as a partnership. The business ordinarily files Form 1065 and provides Schedule K-1 to members, who report their shares of income on their individual or other applicable returns.
Both structures generally use pass-through taxation, meaning business income is reported by the owners rather than subject to regular C Corporation income tax.
For an active sole proprietor, net earnings are generally subject to self-employment tax. For members of partnership-taxed LLCs, the treatment depends on their activities and applicable partnership tax rules.
An LLC may instead elect corporate taxation using Form 8832 or eligible S Corporation treatment using Form 2553.
2. S Corp Taxation: Pass-Through Income, Salary, and Distributions
An S Corporation generally passes taxable business income through to its shareholders. Shareholders report their allocated income on personal tax returns, even when the business retains the cash.
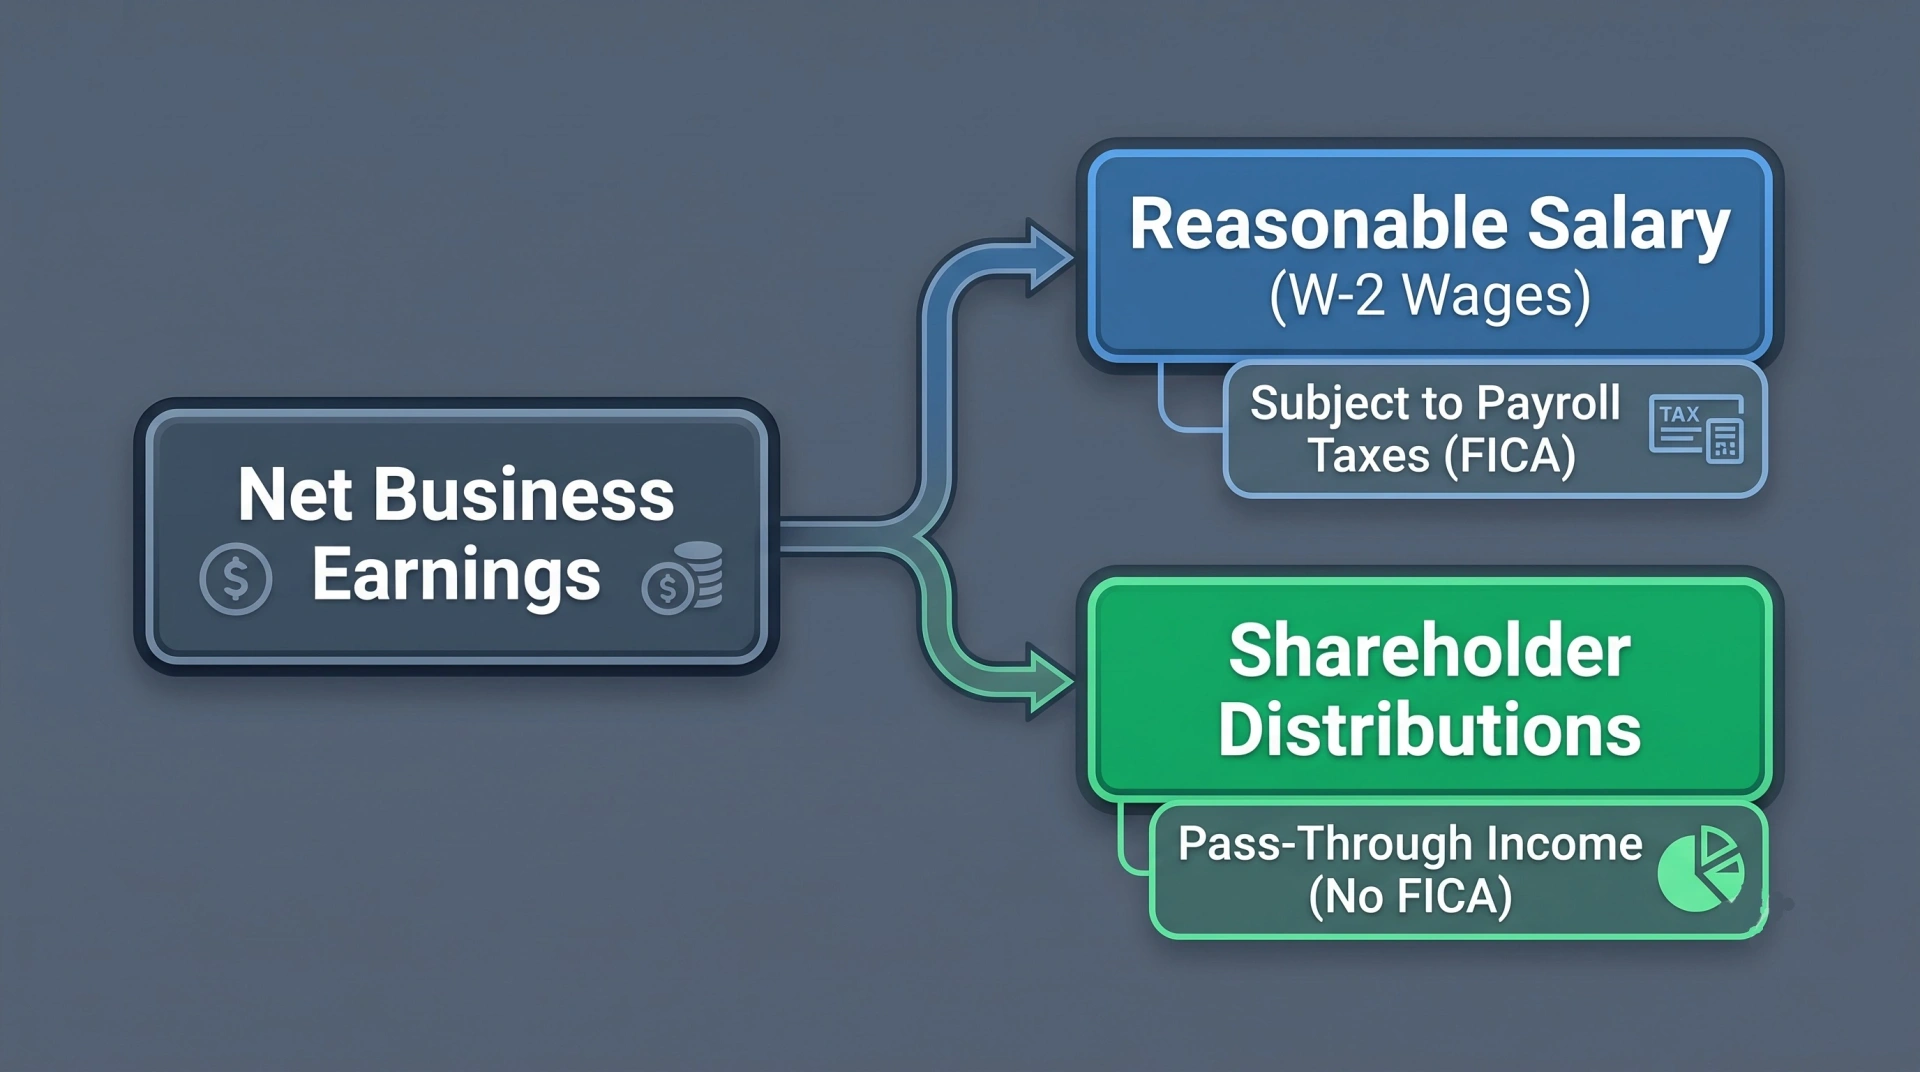
A shareholder who performs substantial services for the business must receive reasonable compensation for those services before taking non-wage distributions.
Salary: Subject to applicable employee and employer payroll taxes.
Distributions: Generally not subject to Social Security and Medicare employment taxes when properly characterized, although pass-through business income remains subject to applicable income taxes.
For example, a business owner might receive $65,000 in W-2 compensation and additional shareholder distributions. Whether that salary is reasonable depends on the services performed, market compensation, responsibilities, and other business circumstances.
The IRS can reclassify distributions as wages if a shareholder-employee receives insufficient compensation.
Importantly, the S Corp tax benefit is not automatic. It must be evaluated against payroll processing, accounting expenses, state taxes, and other compliance requirements.
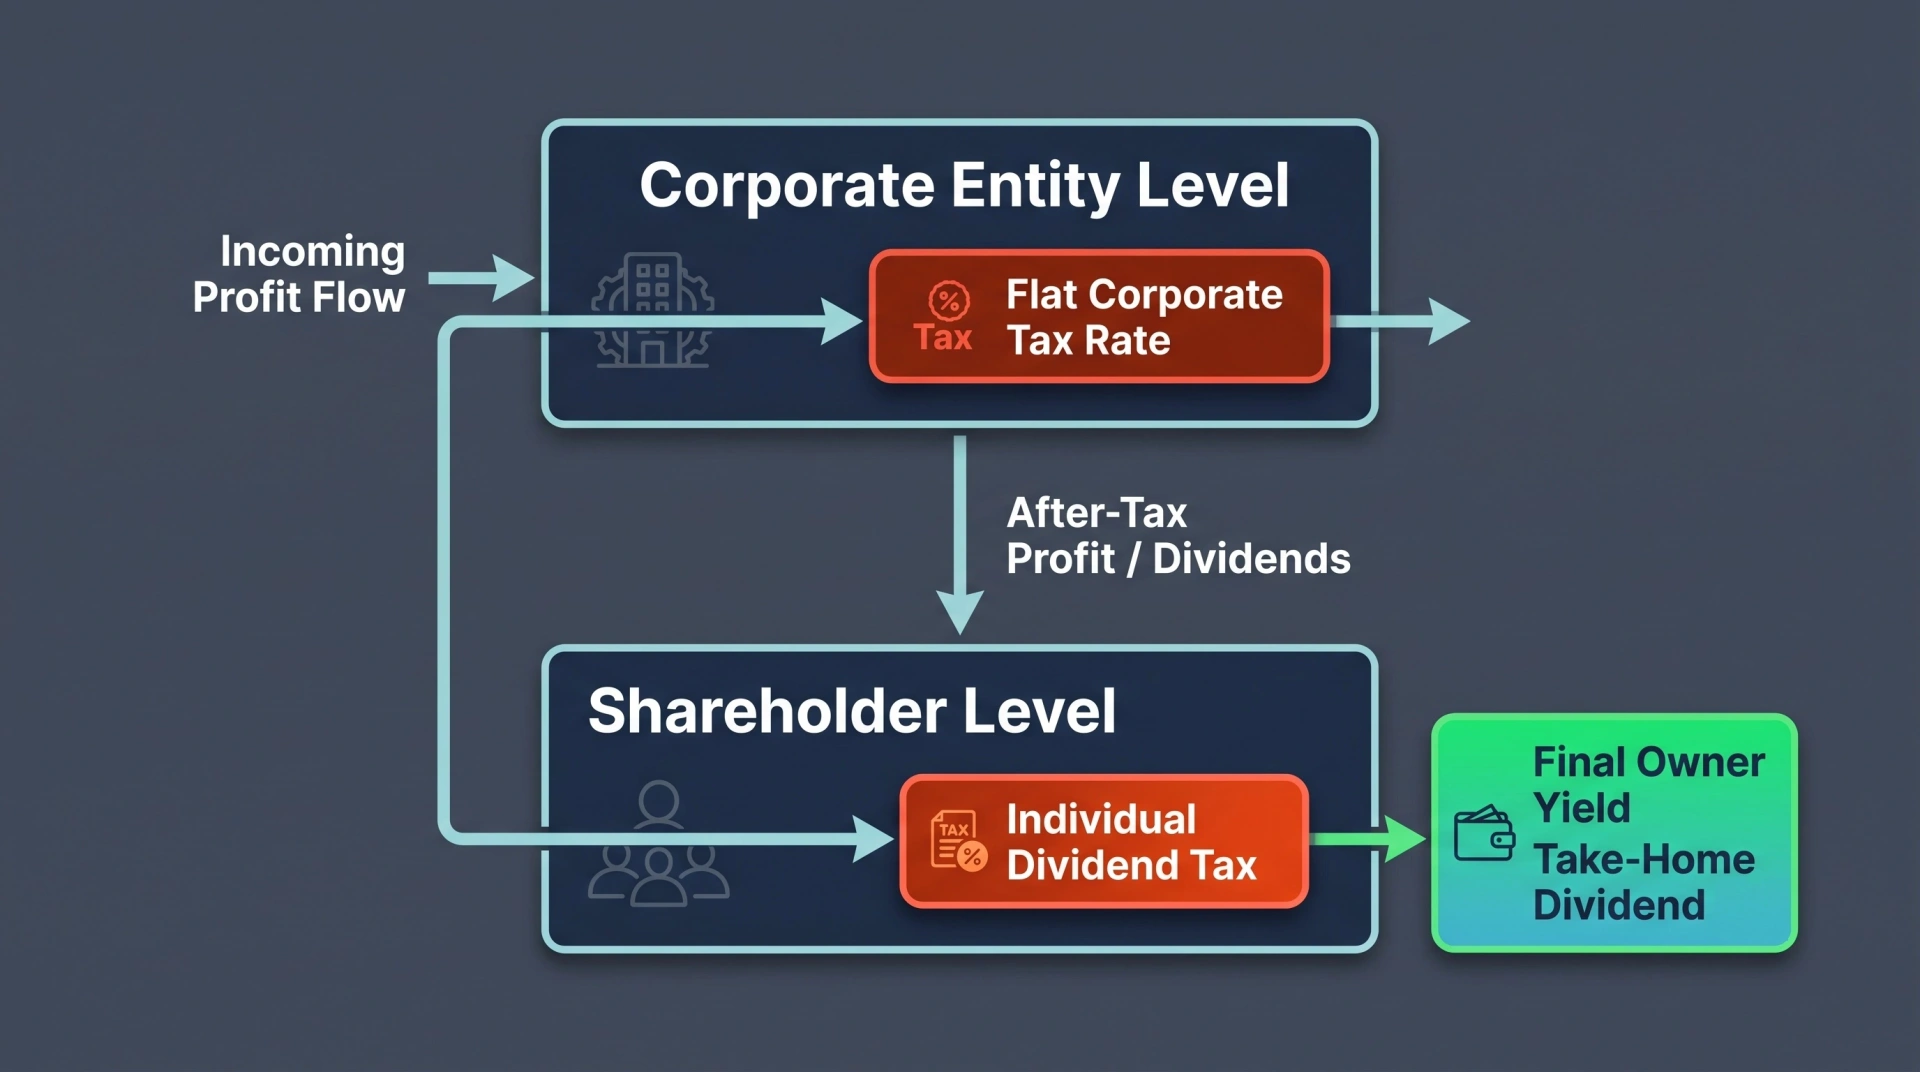
3. C Corp Taxation: Corporate Tax and Double Taxation
A C Corporation pays federal income tax at a flat 21% rate in 2026.
If the corporation retains after-tax earnings for business operations, shareholders generally do not incur dividend tax simply because the business earned that income.
However, when the corporation distributes earnings as dividends, shareholders may incur a second level of tax.
Consider a simplified example:
A C Corporation earns $100,000 in taxable income before federal corporate tax.
Federal corporate income tax at 21%: $21,000.
Remaining earnings: $79,000.
If all remaining earnings are paid as qualified dividends taxed to the shareholder at an assumed 15%, additional dividend tax is $11,850.
Combined illustrative corporate and shareholder federal income tax: $32,850.
The combined rate in this particular scenario is 32.85%, before state taxes or other applicable individual taxes.
This is not a universal effective tax rate. Actual results depend on dividend qualification, individual tax brackets, retained earnings, deductible compensation, and other circumstances.
C Corporations may nevertheless be attractive when ownership flexibility, investor requirements, or a growth strategy outweigh the potential cost of double taxation.
4. Self-Employment Tax vs Payroll Tax
One reason small-business owners compare LLC and S Corp taxation is the different treatment of business earnings for Social Security and Medicare purposes.
For 2026:
The combined self-employment tax rate is generally 15.3%: 12.4% for Social Security and 2.9% for Medicare.
The Social Security wage base is $184,500.
The employee and employer each generally pay 6.2% Social Security and 1.45% Medicare tax on covered wages, subject to applicable limits.
Medicare tax does not have the same wage base limit, and additional Medicare tax may apply at higher income levels.
For a typical self-employed individual, the 15.3% rate is generally applied to 92.35% of eligible net self-employment earnings, subject to applicable limits and adjustments.
An S Corporation instead pays employment taxes on shareholder-employee wages. Proper non-wage distributions generally are not subject to these taxes.
This difference can create savings, but it does not mean all earnings distributed by an S Corp are tax-free.
The Qualified Business Income (QBI) deduction under Section 199A can further affect the comparison.
Eligible owners of sole proprietorships, partnership-taxed LLCs, and S Corporations may qualify for a deduction of up to 20% of qualified business income, subject to taxable-income limitations and other requirements.
C Corporation income does not qualify for this owner-level deduction.
For S Corporation shareholders, reasonable W-2 compensation is excluded from QBI. Other limitations may depend on the type of business, owner income, W-2 wages, and qualified property.
Consequently, electing S Corp taxation can change both employment taxes and the QBI deduction. These effects should be evaluated together.
LLC vs S Corp vs C Corp: Tax Comparison With Examples
A numerical example makes it easier to understand how different entity classifications affect the business owner's financial position.
Consider a hypothetical single-owner consulting business generating $120,000 in annual profit before owner compensation, employer payroll taxes, and entity-specific administrative costs.
Assume:
The business operates in the United States.
The owner actively works in the business.
An illustrative reasonable S Corp salary is $65,000.
There are no other wages or self-employment income.
The full 2026 Social Security wage base remains available.
State taxes and unemployment taxes are excluded.
The additional annual administrative cost of S Corp treatment is assumed to be $2,500.
These assumptions allow an employment tax comparison. They do not provide a complete calculation of the owner's federal income tax.
Tax Comparison for a Business Earning $120,000
Scenario 1: Single-Member LLC With Default Taxation
Assuming the entire $120,000 is eligible net self-employment profit:
Net earnings subject to self-employment tax:
$120,000 × 92.35% = $110,820
Estimated self-employment tax:
$110,820 × 15.3% = $16,955
The owner may generally deduct one-half of the self-employment tax in computing adjusted gross income, subject to applicable rules.
Federal income tax is additional and depends on the owner's full personal tax circumstances.
Scenario 2: LLC Electing S Corp Taxation
Assume the $65,000 salary is supportable as reasonable compensation.
Combined employee and employer Social Security and Medicare taxes:
$65,000 × 15.3% = $9,945
The employer's half of these payroll taxes is $4,972.50, which is generally deductible by the corporation.
The business would have approximately $50,028 remaining before other adjustments and entity-specific costs:
This remaining amount is not automatically the shareholder's taxable income or cash distribution. Taxable income depends on the S Corporation's full accounting and tax adjustments.
Illustrative combined employment tax difference:
$16,955 − $9,945 = approximately $7,010
After assuming $2,500 in additional compliance costs, the preliminary difference is approximately $4,510.
This is a screening result, not the owner's final annual tax savings. It excludes differences in income tax, QBI, deductions, state treatment, and other employment-related costs.
Scenario 3: C Corporation
Assume instead that the corporation has $120,000 in taxable income after all applicable deductible expenses, with no additional owner compensation in this illustrative corporate-tax calculation.
At the 21% federal corporate rate:
$120,000 × 21% = $25,200
Remaining after federal corporate income tax:
$120,000 − $25,200 = $94,800
If these earnings remain in the corporation, there is no immediate shareholder dividend tax from their retention alone.
If the entire $94,800 is distributed as dividends, additional shareholder income tax may apply. At an illustrative qualified dividend rate of 15%, that tax would be $14,220, creating combined corporate and dividend income tax of $39,420.
These examples are not directly equivalent owner-compensation scenarios: the S Corp example pays an owner salary, while the C Corp example isolates entity taxation. A genuine three-way comparison must normalize owner compensation, personal income, deductions, and cash distributions before recommending a structure.
When Does an LLC Benefit From S Corp Taxation?
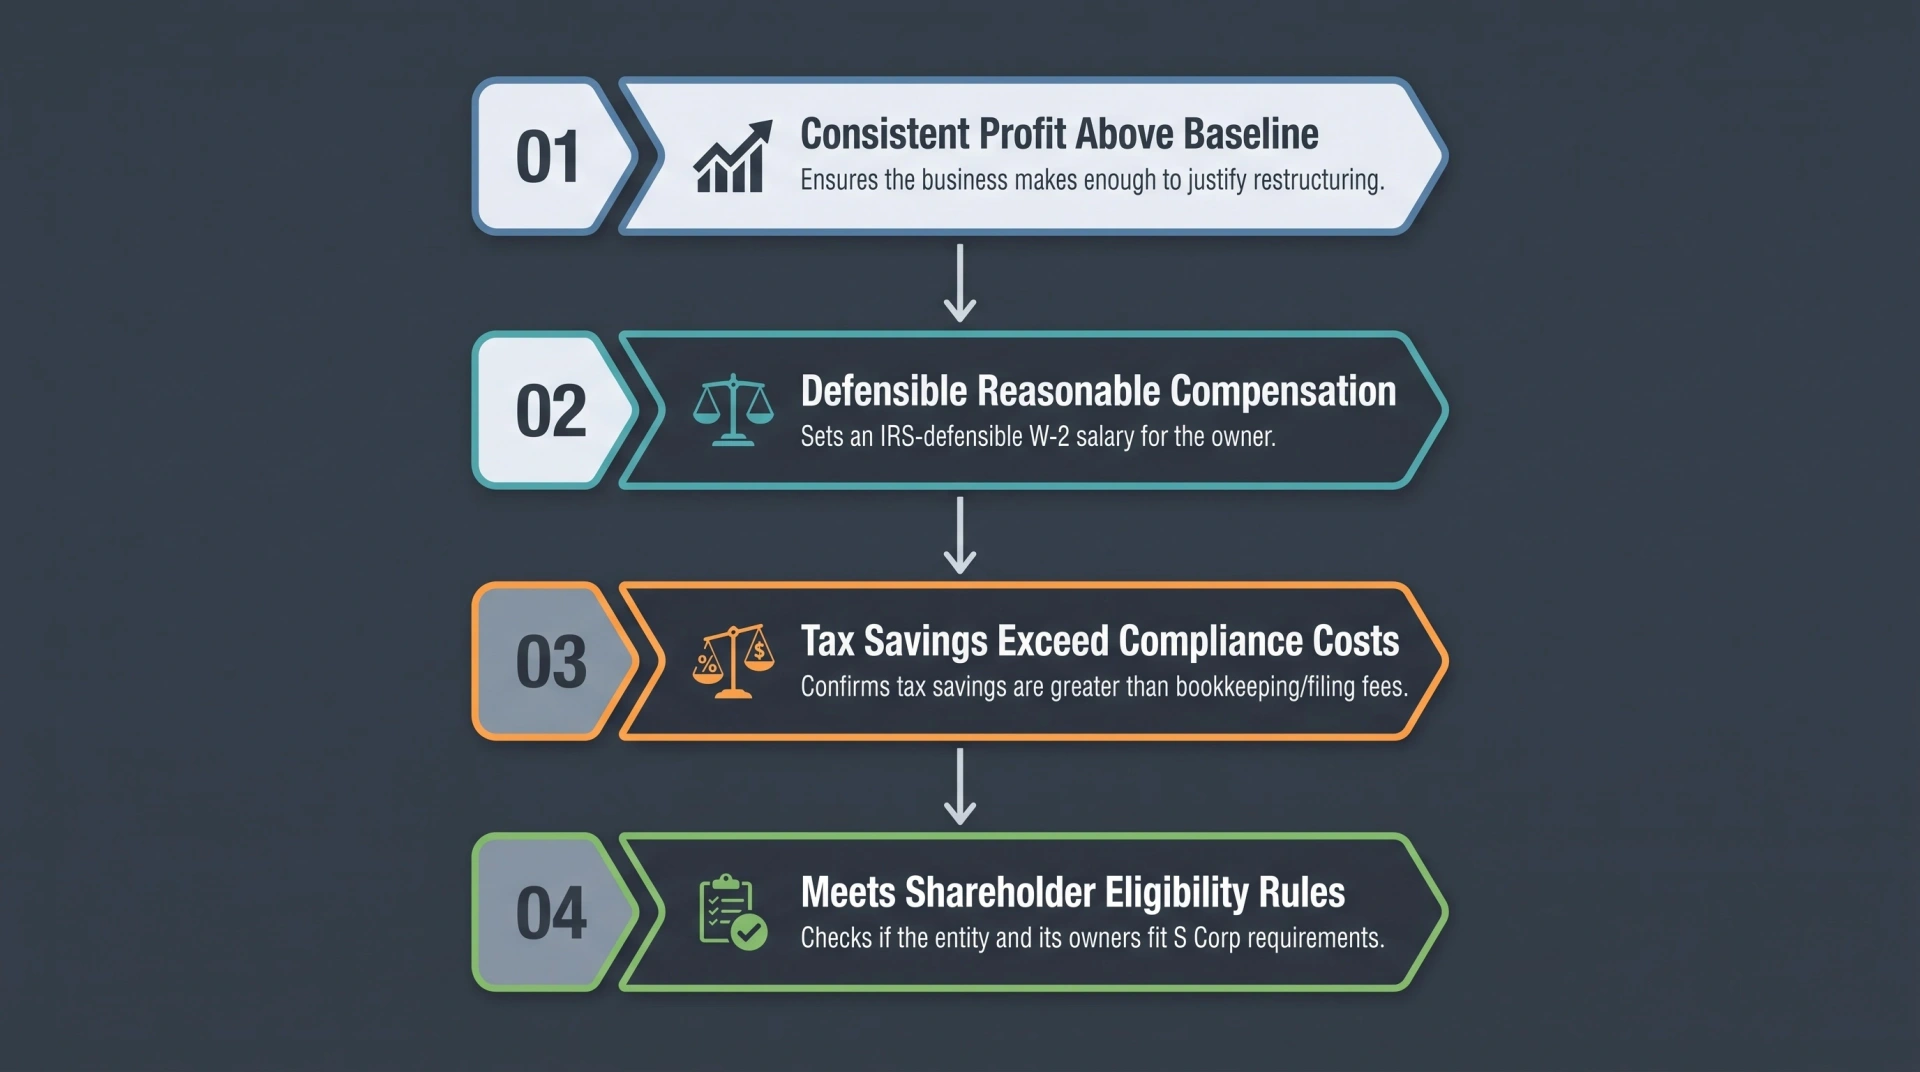
An LLC may benefit from electing S Corp status when it generates consistent earnings materially above reasonable owner compensation.
The potential financial benefit comes primarily from the difference between self-employment tax treatment and the payroll taxes due on reasonable shareholder wages.
However, this benefit must cover the added cost of operating under S Corporation tax rules.
For a business with relatively low profits, a reasonable salary may consume nearly all available earnings, leaving little opportunity for employment tax savings.
For a profitable owner-operated company, the difference can become more meaningful, provided the compensation arrangement is supportable.
There is no universal IRS rule requiring an LLC to earn $60,000, $80,000, or $100,000 before making an S Corp election. Those figures are sometimes used as screening benchmarks, not legal thresholds or guaranteed break-even points.
Reasonable Salary and S Corp Break-Even Calculations
A simplified break-even framework is:
Net estimated benefit = Employment tax savings − Additional administrative costs ± Changes in income and state taxes
A complete analysis should consider:
Reasonable compensation based on the owner's role and market conditions.
Employer and employee payroll taxes.
Social Security wage base limits.
Payroll processing and tax return preparation.
State-level S Corp taxes or entity fees.
QBI deduction differences.
Retirement plan and health insurance treatment.
Business income stability and future growth.
Reasonable compensation is particularly important. An owner cannot choose an artificially low salary solely to increase distributions and avoid payroll taxes.
Documentation may include comparable industry salaries, hours worked, the owner's qualifications, management duties, and how much business income is attributable to personal services.
For tax professionals: CPA Pilot's AI Entity Selection Tool helps compare Schedule C, LLC, S Corp, and C Corp scenarios using client financial information, estimated tax consequences, and relevant non-tax considerations. Its analysis can support a documented recommendation, subject to professional review.
LLC vs S Corp vs C Corp: Ownership, Liability, and Management
Tax savings are only one part of the decision. Ownership rights, liability protection, and fundraising requirements can determine which structure is practical or legally available.
1. Personal Liability Protection
An LLC generally protects members from personal liability for the company's debts and obligations. A corporation generally provides similar limited liability protection to shareholders.
Neither structure guarantees complete protection.
Owners may still face personal liability from personal guarantees, their own misconduct, certain taxes, or circumstances in which courts disregard the separation between the entity and its owners.
An S Corp election does not independently create liability protection. That protection comes from the underlying LLC or corporation under applicable law.
This means an LLC taxed as an S Corp generally retains the state-law liability characteristics of an LLC.
2. Ownership and Shareholder Restrictions
LLCs offer considerable ownership flexibility. Subject to applicable law, owners may include individuals, corporations, partnerships, and foreign investors.
S Corporations face stricter federal eligibility rules.
An S Corporation generally must:
Be an eligible domestic entity.
Have no more than 100 shareholders, subject to permitted family-counting rules.
Have only eligible shareholders, generally certain individuals, estates, trusts, and qualifying exempt organizations.
Have no nonresident alien shareholders.
Have only one class of stock for economic rights, although voting rights may differ.
C Corporations generally allow more flexible shareholder types, larger ownership structures, and multiple equity classes.
These differences can rule out S Corp treatment for businesses planning certain investor arrangements, even when pass-through taxation appears attractive.
3. Management and Profit Distribution Rules
An LLC may be member-managed or manager-managed, depending on its operating agreement and state law.
Multi-member LLCs taxed as partnerships may also provide flexibility in how profits, losses, and distributions are allocated, subject to partnership tax rules.
Corporations generally operate through a board of directors, officers, bylaws, and shareholder governance procedures.
S Corporations must preserve identical economic rights to distributions and liquidation proceeds across their outstanding shares. This restricts certain arrangements that may be available to partnerships or C Corporations.
An LLC that elects S Corp taxation must comply with these federal requirements even if state LLC law would otherwise permit more flexible allocations.
4. Raising Capital and Issuing Stock
A C Corporation is often preferred by businesses planning venture capital financing because it can issue different classes of stock, including common and preferred shares.
This flexibility may support liquidation preferences, investor protections, stock options, and multiple financing rounds.
S Corporations generally cannot issue multiple classes of stock with different economic rights. Their shareholder eligibility restrictions can also complicate institutional investment.
LLCs may admit investors through membership interests, but some venture capital investors prefer corporate equity structures for legal, administrative, and tax reasons.
For founders considering an eventual sale, C Corporation stock may also qualify for special tax treatment under Section 1202, Qualified Small Business Stock (QSBS).
Depending on the stock acquisition date and statutory requirements, eligible shareholders may qualify for a partial or full exclusion of qualifying capital gains. Stock issued after July 4, 2025, may be subject to newer eligibility thresholds and holding-period provisions.
QSBS benefits are not automatic. The corporation, stock issuance, shareholder, business activities, and holding period must satisfy the applicable rules. This is an important consideration for qualifying growth companies but is generally less central to the decision of a small service business without an equity exit strategy.
What Does It Cost to Maintain an LLC, S Corp, or C Corp?
The total cost of a business structure includes formation expenses, recurring state requirements, tax preparation, bookkeeping, and payroll obligations.
The cheapest structure to establish is not necessarily the most economical over time.
1. Formation and State Filing Fees
LLCs generally form by filing Articles of Organization with the appropriate state agency. Corporations typically file Articles of Incorporation or equivalent formation documents.
Fees vary by state and can include registered agent expenses, required reports, licenses, and other administrative charges.
An S Corp election itself does not create a new state-law entity. A qualifying existing LLC or corporation may be able to elect S Corp treatment without forming another company.
State selection also matters. Forming in Delaware or Wyoming does not automatically eliminate registration, taxation, or reporting responsibilities in the state where the business actually operates.
2. Annual Compliance and Administrative Costs
A default-taxed single-member LLC often has relatively straightforward federal tax reporting. The actual cost depends on transaction volume, employees, state filings, and bookkeeping requirements.
An LLC taxed as an S Corp usually requires payroll administration, a separate federal S Corporation return, and additional documentation of shareholder compensation and distributions.
A C Corporation must maintain appropriate records, comply with corporate governance requirements, and prepare its own corporate tax return.
Rather than relying on a generic national average, owners should obtain estimates for their specific business and state.
3. Tax Returns and IRS Filing Requirements
The federal filing requirements differ according to tax classification:
Tax treatment
Principal federal income tax filing
Individual-owned single-member LLC, default status
Form 1040, usually Schedule C for active business income
An eligible business generally requests S Corp status using Form 2553. An eligible LLC may use Form 8832 to elect classification as a corporation taxable under C Corporation rules.
An LLC that properly files Form 2553 generally does not need a separate Form 8832 solely to obtain the underlying corporate classification.
The standard S election deadline is generally no later than two months and 15 days after the beginning of the tax year for which the election is intended to take effect, with additional rules and possible late-election relief.
Businesses with employees may also have payroll reporting requirements, including Forms 941, 940, and W-2 where applicable.
State income taxes, franchise taxes, and annual reports are separate from federal IRS filing requirements.
Which is Better: LLC, S Corp, or C Corp?
The best structure is the one that accommodates the business's legal and ownership requirements while producing an appropriate after-tax result at an acceptable administrative cost.
When is an LLC the Best Choice?
A default-taxed LLC is often a practical choice for a freelancer, consultant, independent contractor, or small business owner who wants limited liability protection and flexible operations.
It may be especially appropriate when:
The business is new or earnings are inconsistent.
Owners want relatively simple administration.
Multiple members need flexible economic arrangements.
There is no immediate requirement for corporate stock.
Additional S Corp payroll costs would outweigh projected savings.
For example, a solo consultant earning $45,000 in annual business profit may find default LLC taxation more practical than an S election, particularly if reasonable compensation would absorb most of those earnings.
The correct choice still depends on state costs, other personal income, and the owner's circumstances.
When Should an LLC Elect S Corp Taxation?
An S Corp election may be appropriate for an established business with reliable profitability, eligible owners, and enough earnings above reasonable owner compensation to justify the additional compliance burden.
Consider an owner-operated professional services firm generating $180,000 in annual profit before owner compensation.
If the owner's responsibilities support a reasonable salary significantly below that amount, some remaining business earnings may be distributable without additional Social Security and Medicare employment taxes.
The owner must still account for income tax, payroll requirements, and the applicable QBI calculation.
An S Corp election can be especially worth evaluating when annual profitability has increased substantially and is expected to remain stable.
However, service businesses highly dependent on the owner's labor may require substantial compensation, reducing the available tax benefit.
When is a C Corp the Best Choice?
A C Corporation may be the stronger fit when the business needs a capital structure capable of supporting multiple stock classes, institutional funding, and complex equity arrangements.
Common situations include:
A technology startup preparing for venture capital investment.
A business planning several equity financing rounds.
A company with investors who cannot hold S Corp shares.
A business considering an IPO or major stock-based exit.
A qualifying company evaluating potential QSBS benefits.
The 21% corporate income tax rate can also be relevant to a strategy involving retained earnings. However, the full tax consequences of paying owners, distributing dividends, and eventually selling the business must be modeled before treating corporate taxation as advantageous.
Choosing Based on Profit, Ownership, and Growth Plans
Before making an entity decision, evaluate five questions:
How much profit does the business realistically expect to earn?
Stable earnings matter more than a single profitable month or quarter.
How much reasonable compensation would working owners require?
This is essential when evaluating S Corp savings.
Who owns or may invest in the business?
Foreign ownership, investor entities, and preferred equity may affect eligibility.
Will profits be distributed or retained?
The answer influences both immediate and longer-term tax exposure.
What will the structure cost to operate?
Include state taxes, bookkeeping, payroll, tax preparation, and governance requirements.
A structure that works for a sole proprietor may not suit a venture-backed startup. Likewise, a business that begins with default LLC taxation may benefit from reconsidering its election as earnings and ownership needs change.
Can You Switch From an LLC to an S Corp or C Corp?
Yes. A business may be able to change its federal tax classification or convert its underlying legal entity, but these are not the same transaction.
For example, an eligible LLC may elect S Corporation taxation using Form 2553 while remaining an LLC under state law.
An LLC may also elect C Corporation tax classification using Form 8832, subject to IRS rules and restrictions on changing classifications.
A legal conversion from an LLC into a state-law corporation is different. It may require state conversion documents, amendments to ownership arrangements, and a review of potential tax consequences.
Certain changes in classification can be treated as deemed transfers or liquidations for federal tax purposes. Converting an S Corporation into C Corporation taxation can also involve special tax consequences, including built-in gains considerations in relevant circumstances.
Owners should review the transaction before making an election or conversion, particularly when the business has appreciated assets, accumulated earnings, multiple owners, or plans to raise capital.
An LLC with default taxation may be simpler and less expensive to administer, while an eligible LLC taxed as an S Corporation may reduce employment taxes when profits exceed reasonable owner compensation. The better option depends on total federal and state taxes, QBI deduction effects, and added compliance costs. An LLC can retain its legal structure while electing S Corp taxation.
How Much Profit Should an LLC Make Before Electing S Corp Status?
There is no fixed IRS profit threshold for electing S Corp status. The decision depends on whether expected employment tax savings exceed payroll and administrative costs after accounting for reasonable compensation, federal income taxes, deductions, and state rules. Consistent profitability and a defensible salary are more useful decision factors than a universal revenue benchmark.
Can a Single-Member LLC Be Taxed as an S Corp?
Yes. A single-member LLC may elect S Corporation taxation if it meets the applicable IRS eligibility requirements and properly files Form 2553. The owner may need to receive reasonable W-2 compensation for services performed, and the business must comply with S Corporation tax filing and payroll requirements.
Compare Business Structures With CPA Pilot
Choosing between an LLC, S Corp, and C Corp requires more than comparing headline tax rates.
For tax professionals advising business owners, a sound recommendation should account for owner compensation, tax elections, state-level implications, administrative costs, liability considerations, and future growth.
CPA Pilot's AI Entity Selection Tool is designed to help CPAs and tax professionals evaluate Schedule C, LLC, S Corp, and C Corp scenarios using client financial information and business goals.
The tool provides comparative tax analysis, considers relevant non-tax factors, and generates a structured, client-ready recommendation that professionals can review and discuss with their clients.
The right structure is not simply the one with the lowest advertised tax rate. It is the one that supports the business's ownership requirements, expected profitability, financial strategy, and long-term objectives while meeting applicable federal and state rules.
Tax information reviewed against available IRS guidance for 2026. Examples are illustrative and do not constitute individualized tax or legal advice. Tax results depend on the taxpayer's specific facts, elections, state requirements, and applicable law. Professional review is recommended before formation, election, or conversion decisions.
Key Takeaways
4 essential insights
Pick LLC for flexible management, simple default taxes, and liability protection.
Elect S Corp if profits justify payroll costs and enable tax savings.
Choose C Corp when raising outside capital or issuing multiple stock classes.
Separate legal structure from tax status; LLC can elect S Corp taxation.
I’m Harsh Mody, CPA, founder of CPA Pilot—an AI Tax Assistant for CPAs, Enrolled Agents, and U.S. tax firms. With 18+ years in accounting, tax auditing, consulting, and product management, I’ve seen how compliance-heavy work limits true advisory impact. I built CPA Pilot to change that—by applying AI-driven tax research, deduction optimization, and IRS/state code automation to help firms unlock tax savings and scale advisory services with speed and accuracy.