Definition
Tax Apportionment
What is Tax Apportionment?
Tax apportionment is the process of determining how much of a multistate business's income is attributable to a particular state for income tax purposes. States use prescribed formulas based on sales, property, payroll, or a combination of these factors to calculate the share of apportionable business income assigned to their jurisdiction.
When Does Tax Apportionment Apply?
Tax apportionment generally becomes relevant when a business conducts taxable activities in multiple states and must determine the portion of its income attributable to each jurisdiction.
A business's state income tax obligations depend on several considerations:
Tax nexus: Whether a business has a sufficient connection with a state for that jurisdiction to impose tax.
Federal limitations: Constitutional and statutory restrictions, including Public Law 86-272, which limits certain state income taxes on qualifying sellers of tangible personal property.
Income classification: Whether income must be apportioned among states or allocated directly to a particular jurisdiction.
Under applicable state rules, income generally falls into two relevant categories:
Apportionable business income: Income associated with business operations that is divided among jurisdictions using a prescribed formula.
Non-business income: Income that does not qualify as business income under applicable state law and is assigned to a particular jurisdiction under that jurisdiction’s allocation rules.
California's Schedule R instructions explain these classifications and their treatment when determining California-source income.
State apportionment requirements can affect C corporations, S corporations, partnerships, LLCs, and sole proprietors, depending on their activities, tax classification, and applicable state law.
For additional context, see how pass-through entities are taxed and the broader differences between federal and state taxation.
How is Tax Apportionment Calculated?
Tax apportionment is calculated by multiplying a business's apportionable income by the state's applicable apportionment factor. The factor represents the proportion of business activity attributed to that state under its prescribed formula.
The standard tax apportionment formula is:
Apportioned Income = Apportionable Income x Apportionment FactorThe percentage is determined using the factors prescribed by state law. Two commonly recognized methods are the single-sales factor and the traditional three-factor formula.
Single-Sales Factor Formula
The single-sales factor formula measures sales attributed to a particular state against the total sales included in the applicable sales factor.
Single-Sales Factor Formula
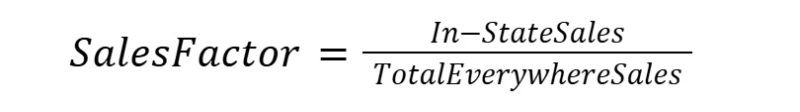
The denominator represents everywhere sales included in the applicable state's sales factor.
Determining which receipts qualify as in-state sales requires applying the jurisdiction's sales sourcing rules:
Sales of tangible goods: Often sourced to the destination state where goods are delivered, although some states apply origin-based, throwback, or other special sourcing rules.
Sales of services: Under market-based sourcing, receipts are generally assigned to the state where the customer receives the service or its benefit, as defined by applicable law.
Receipts from intangible property: May be assigned according to where intangible property is used or other state-prescribed sourcing methods.
A business's office location or the state where employees perform services does not necessarily determine where its service revenue is sourced.
Three-Factor Apportionment Formula
The three-factor apportionment formula calculates a business's apportionment percentage using its property, payroll, and sales attributed to a state.
Under the traditional equally weighted method:
Three-Factor Apportionment Formula
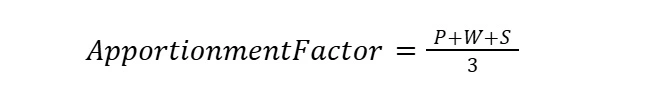
Where:
P: Property Factor: Qualifying in-state property divided by qualifying property everywhere.
W: Payroll Factor: In-state compensation divided by total compensation included in the factor.
S: Sales Factor: In-state sales divided by total sales included in the factor.
Each factor is calculated separately and expressed as a decimal or percentage before averaging.
Some jurisdictions use differently weighted formulas or specialized methods for particular industries. The treatment of missing or zero-denominator factors also depends on applicable state rules.
California requires an apportioning trade or business that derives more than 50% of its gross business receipts from qualified agricultural or extractive business activities to use an equally weighted three-factor formula. For a unitary group, the qualifying-business-activities test generally considers the group's business receipts.
For taxable years beginning on or after January 1, 2025, savings-and-loan and banking or financial business activities are no longer included among California's qualified business activities for this exception.
These requirements are addressed in the California Franchise Tax Board's apportionment and allocation guidance.
Tax Apportionment Calculation Example
Consider a hypothetical multistate business with $500,000 in apportionable income. Assume State A uses the single-sales factor method and that all the following sales are included in the applicable factor.
Component | Amount |
Total apportionable business income | $500,000 |
Sales attributable to State A | $300,000 |
Total everywhere sales included in the sales factor | $1,000,000 |
Apportionment percentage | 30% |
Income apportioned to State A | $150,000 |
Step 1: Calculate the sales apportionment factor.
Sales Factor= $300,000 / $1,000,000 = 0.30= 30%Step 2: Calculate the income apportioned to State A.
Apportioned Income =$500,000 x 0.30 = $150,000Result: The business apportions $150,000 of its income to State A under the stated assumptions.
This amount represents apportioned income, not the final state income tax owed. The actual tax liability may depend on applicable state income adjustments, tax rates, credits, and other requirements.
What is the Difference Between Tax Allocation & Apportionment?
Tax allocation assigns qualifying income directly to a jurisdiction, while tax apportionment divides apportionable business income among jurisdictions using a prescribed formula.
Tax allocation | Tax apportionment |
Assigns qualifying income to a particular jurisdiction | Divides income among jurisdictions using a formula |
Generally applies to income classified as nonbusiness income under applicable state law | Generally applies to apportionable business income |
Uses income-specific assignment rules | Uses prescribed factors such as sales, property, or payroll |
Example: Suppose a company earns operating profits across multiple states and separately receives rental income from property located in one state.
The operating profits may be apportioned among the relevant jurisdictions. If the rental income qualifies as nonbusiness income under applicable law, it may instead be allocated to the state where the property is located.
Rental income is not automatically nonbusiness income merely because it arises from property. Its classification depends on the relevant facts and state law.
California's apportionment and allocation guidance explains how these methods contribute to determining California-source net income.
Tax Apportionment FAQs
Does tax apportionment apply to LLCs and partnerships?
Yes. LLCs and partnerships with multistate business activities may be subject to apportionment requirements. Treatment depends on the entity's tax classification, applicable state law, and how its income is reported.
Is tax nexus the same as tax apportionment?
No. Nexus concerns a state's sufficient connection to impose tax, subject to legal limitations. Apportionment determines the share of business income attributable to that state.
Can two states tax the same business income?
Yes. Different tax bases, sourcing rules, and apportionment formulas can cause overlapping taxation. Credits for taxes paid to other states and interstate agreements may reduce, but not always eliminate, double taxation.
Do all states use the same tax apportionment formula?
No. States may use single-sales, three-factor, differently weighted, or industry-specific formulas. The applicable method can vary by jurisdiction, business activity, and tax year.
How are service sales sourced for state tax apportionment?
Many states use market-based sourcing, attributing service receipts to where customers receive the service or its benefit. Other methods may apply depending on state law and the service involved.